An unclaimed money scam wraps a lie inside a truth. Real unclaimed property does exist (forgotten bank accounts, old deposits, uncashed checks), and US state programs let you search and claim directly for free. Start through your state's own agency or the NAUPA directory, never a link in an unexpected message. The scam version calls or texts you, invents urgency, and charges a "processing fee" to release funds that were never there. A letter from the company that held your money can be genuine and is worth verifying; an unexpected call or text with a link or a fee is the red flag.
Read the image explanation
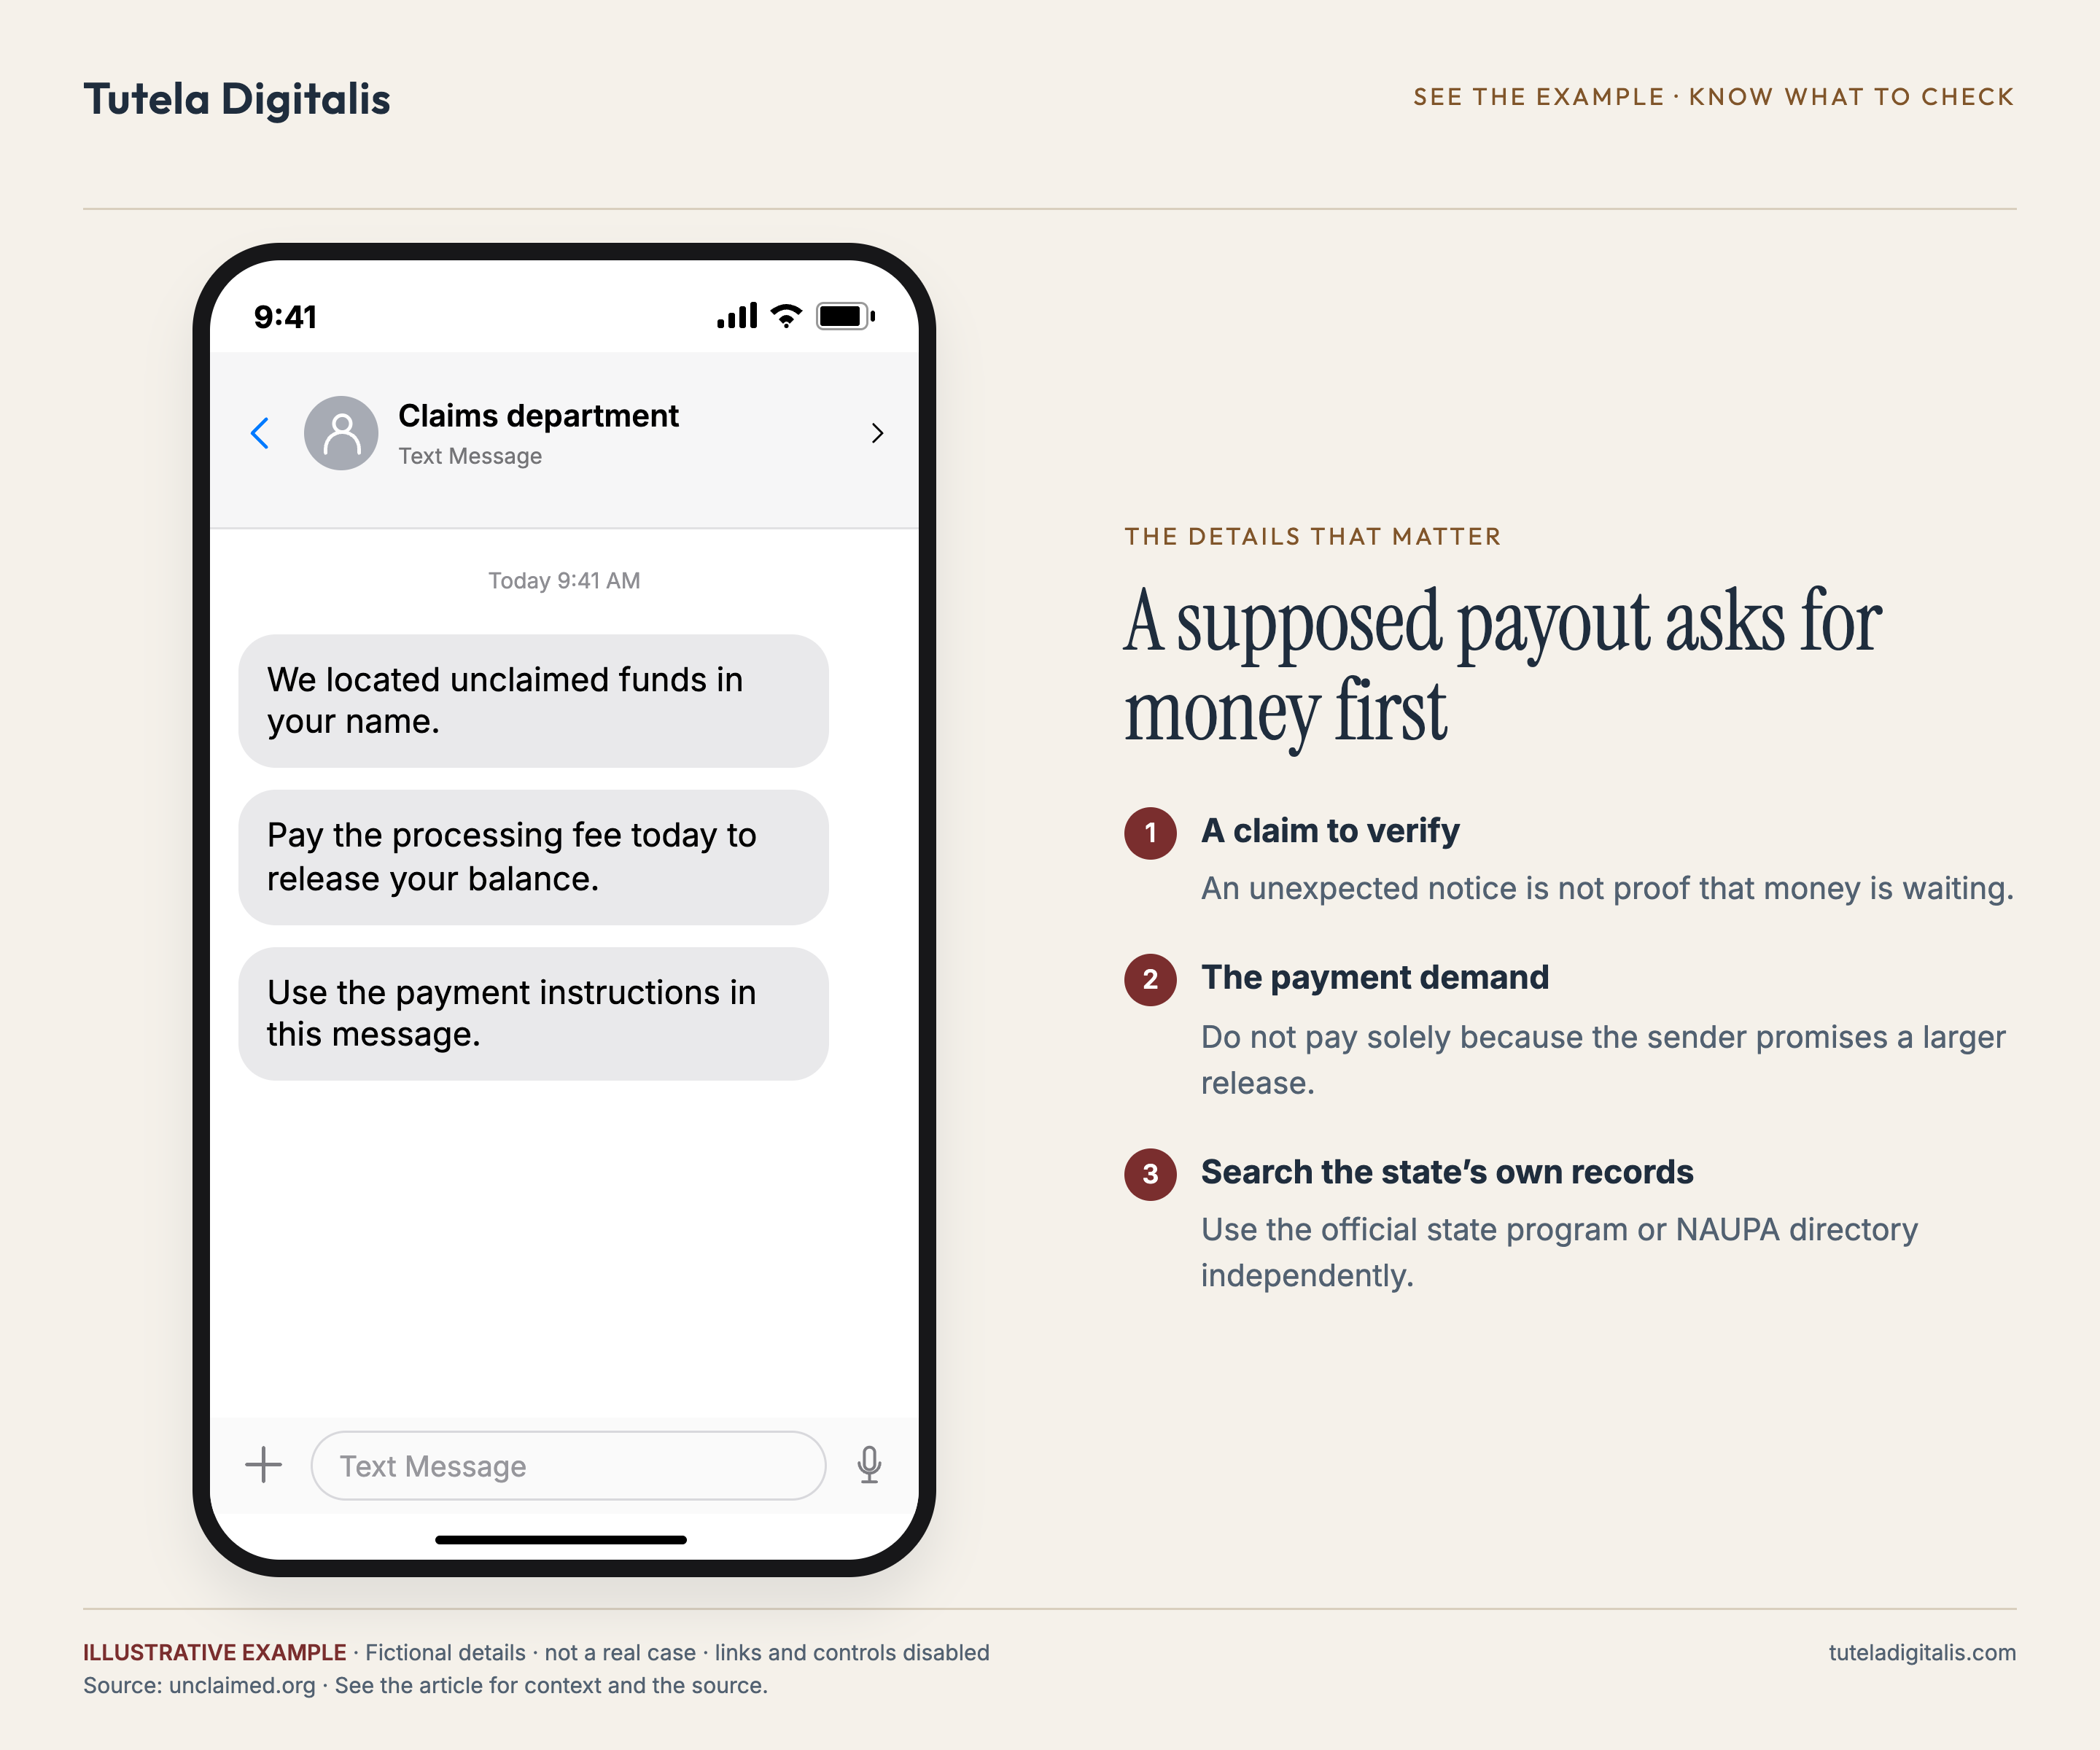
Illustrative example: We located unclaimed funds in your name. Pay the processing fee today to release your balance. Use the payment instructions in this message.
- A claim to verify. An unexpected notice is not proof that money is waiting.
- The payment demand. Do not pay solely because the sender promises a larger release.
- Search the state’s own records. Use the official state program or NAUPA directory independently.
“State unclaimed property programs won’t text you with alerts about unclaimed property — but a scammer will.”
Federal Trade Commission, consumer alert on unexpected calls about unclaimed funds (March 2026)
Most scams rely on a lie you could catch if you slowed down. A foreign prince does not need your checking account. A tax agency does not accept payment in gift cards. The shapes are absurd once you see them. The unclaimed money scam is more dangerous than any of these, and for one specific reason: the thing it dangles in front of you is real.
Unclaimed property is a genuine, well-documented, slightly boring part of American finance. States hold billions of dollars of it. So when a text or a recorded voice tells you that you have $1,840 in unclaimed funds waiting to be released, it is not pinging a fantasy. It is pinging something you may have half-heard was true. That flicker (wait, could I?) is not a flaw in your judgment. It is the exact reaction the scam is engineered to produce.
The scheme was common enough in early 2026 that the Federal Trade Commission issued a consumer alert about it. If you received the call or the text and felt a small jump of hope, or if you have already followed the link and entered something, you were not being foolish. You were responding reasonably to a message designed to look exactly like a piece of luck. If you need it now, skip ahead to if you've already paid or shared your details.
First, the part that is not a scam
It helps to understand the real thing the scam is imitating, because the differences are what save you. Unclaimed property is money or assets that a company lost track of and, after a period of inactivity, was legally required to hand over to the state. A dormant savings account. A final paycheck nobody cashed. A utility deposit, an insurance payout, the forgotten contents of a safe-deposit box. The business cannot keep it: it goes to the state, which holds it until the rightful owner comes to claim it.
The scale is real. The National Association of Unclaimed Property Administrators, the body that coordinates state unclaimed-property offices, runs MissingMoney.com so you can search most states at once, and its guidance is unambiguous: there is no fee to search for and claim your unclaimed property if you use your official state program. Checking really is worthwhile.
But two facts about the real version matter most, because they are precisely what the scam gets wrong. The state route is free. And the government won't call or text and ask you to pay to search for unclaimed funds, or pressure you to respond right away. The FTC put it bluntly in a March 2026 consumer alert: state unclaimed-property programs won't text you with alerts about unclaimed property, but a scammer will.
There is one genuine exception, and it usually travels by post. A business may try to reach an owner before transferring property to the state; North Carolina's guidance for holders, citing General Statute 116B-59, says the law requires a holder to send a written notice to the owner at their last known address. So a mailed letter from the named business that actually held your money is a real category, and it deserves verifying rather than shredding. A call, a text or an email announcing a windfall is not. We take the most common example apart in our guide to the Pathward unclaimed property letter.
How the unclaimed money scam works
The scam takes that legitimate service and reverses every part of it. The structure barely changes from one version to the next:
There is one distinction worth keeping straight. An optional private finder, a business that offers to locate and claim property for a share of it, is a different service from a scammer's release fee. NAUPA says finders are not required and are in most cases legal, and advises checking with the state before signing a finder agreement. If you consider one, ask what property has been identified, how the fee is calculated and which state's rules apply. And a complex estate claim can involve separate document or legal costs, so "free state claim" does not mean every estate expense is zero.
The red flags, hiding in plain sight
Almost every version of this scam fails against one short checklist. Any single item here is reason enough to stop and walk away:
Do not use their link, their phone number, or their form: ignore the message completely. If you genuinely want to know whether you have unclaimed money, go and check yourself, through the official channel, on your own initiative. The real answer is always waiting for you, for free, at your state's program. The scammer is counting on you to act inside the channel they built. Step outside it and the scam has nothing left to stand on.
If you have already paid or shared your details
If you paid a fee or entered your information, do not spiral, but do move quickly. The faster you act, the more of this you can contain:
If you shared sensitive information, the exposure is the part to take seriously: our identity theft guide covers freezing your credit, locking down accounts, and catching the first signs of misuse. And wherever you are in the world, our reporting directory lists the right authority to report this scam to in your country.
How to actually check for unclaimed money, for free
Here is the good news the scam tries to steal from you: checking for unclaimed money is genuinely worthwhile, and it costs nothing. If that call or text planted a seed of curiosity, satisfy it the safe way.
Where this fits in the bigger picture
Strip away the costume and the unclaimed money scam is a phishing scam: an unsolicited message engineered to harvest your data and your money. It belongs to the same family as the government-impersonation calls we took apart in our digital arrest breakdown, and it runs on the machinery covered in our phishing guide: a believable hook, a fake link, a manufactured deadline. The hook here is simply unusually good, because it is shaped like something true.
Hold on to the one rule and this scam falls apart the moment it reaches you: money that genuinely belongs to you is free to claim from your state, and you can always go and find it yourself.
Not sure if that "unclaimed funds" message is real? Let's check it together.
Forward us the text, describe the call, or paste the link you were sent. A real person reviews every case and replies within 24 to 48 hours. Free, confidential, no pressure.
Common questions about unclaimed money scams
Is unclaimed money actually real, or is the whole thing a scam?
Unclaimed money is completely real. When a bank account, paycheck, deposit, or insurance payout goes inactive for long enough, the business is required by law to hand it to the state, which holds it until the owner claims it. States hold billions of dollars of it, and you can search your state's official program for free. What is fake is never the existence of unclaimed property; it is the unexpected call, text, or email claiming to deliver it to you for a fee. The real thing sits in a state database, and you can go and find it yourself.
I got a call or text saying I have unclaimed funds. Is it a scam?
Treat an unexpected call, text or email as a scam until you have verified it yourself. The reliable rule here is about channel, not merely about who contacted whom. The FTC said it plainly in a March 2026 alert: state unclaimed-property programs won't text you with alerts about unclaimed property, but a scammer will. Posted mail is the exception in both directions: the company still holding your money is legally required to write to you before handing it to the state, and some state offices write to owners too, California among them. So a letter is worth verifying rather than binning, while a message with a link or a sense of urgency is the red flag itself. Whatever the channel, the fee test holds: searching for and claiming property through your state's official program is free.
They want a processing fee to release my unclaimed money. Is that normal?
No, it is the heart of the scam. The FTC says that if a caller asks for an upfront 'processing' fee to release the funds, that's a scam, and that the government won't call or text and ask you to pay to search for unclaimed funds. Claiming through your state's official program is free. A small fee feels reasonable next to a few thousand dollars in promised funds, and that contrast is the trick. (An optional private finder is a different thing: NAUPA says finders are in most cases legal, though never required. But a stranger demanding a release fee is not a finder.)
How do I check for unclaimed money safely and for free?
Go to it yourself, through official channels, never through a link someone sent you. Every US state runs an official unclaimed-property program, usually through the state treasury; start from the NAUPA directory at unclaimed.org or your state government's own site. To search many states at once, use MissingMoney.com, NAUPA's official multi-state search. Check every state you have lived or worked in. It is free, and you never need to pay a finder a percentage, although NAUPA notes that third-party finders are in most cases legal if you choose one. Some official services use domains other than .gov, so follow the agency's own link rather than judging by the suffix.
I already paid the fee or entered my details. What should I do now?
Act quickly. If you paid, contact your bank or card provider right away, say the word fraud, and ask what can be stopped, recalled or disputed. If you entered personal details like your Social Security number, date of birth, or banking information, treat your identity as exposed: in the US, IdentityTheft.gov builds a recovery plan; consider a credit freeze, turn on two-factor authentication, and watch your accounts. Save screenshots of everything and report it to the FTC at ReportFraud.ftc.gov and your state attorney general. Finally, ignore anyone who later offers to recover your money for an upfront fee; that is simply the same scam coming back for a second pass.
What if a real notice asks for my Social Security number?
A genuine claim process may need identity evidence. Verify the agency and portal independently first, ask what is necessary and how to submit it securely, and do not send sensitive documents back to an unverified caller or message.
Sources & further reading
Drawn from these authorities, rechecked 16 October 2026. Click any of them to verify.