THE SILENT CHARGEUpdated October 16, 202612 min read
It said “free.” Two years later, you’re still paying.
You signed up for a $0.99 trial, just to see. The charge two weeks later was small. So was the one next month, and the one after. By the time you noticed the bill, you had been paying $14.99 a month for nineteen months for a service you used twice. Welcome to the subscription trap: the most legal-looking scam in your inbox.
$2.5B
Amazon's 2025 Prime settlement (FTC)
23
Screens to cancel Uber One, per the FTC
60 days
US credit-card written dispute window (CFPB)
GONE
2024 "Click to Cancel" rule, vacated July 2025
The short answer
A subscription trap is a free trial, $0.99 promo, or pre-checked checkout box that quietly enrolls you in an ongoing monthly charge, with the recurring price buried, the cancellation flow built to discourage you, and the bill kept just small enough that you do not notice for months. To get out, document cancellation with the merchant and separately ask your bank or card issuer to stop the recurring payment; replacing the card may not stop it. The 2024 “Click to Cancel” rule was vacated in July 2025, but ROSCA and other protections still apply, and an incorrect charge can still be disputed on the facts of your case.
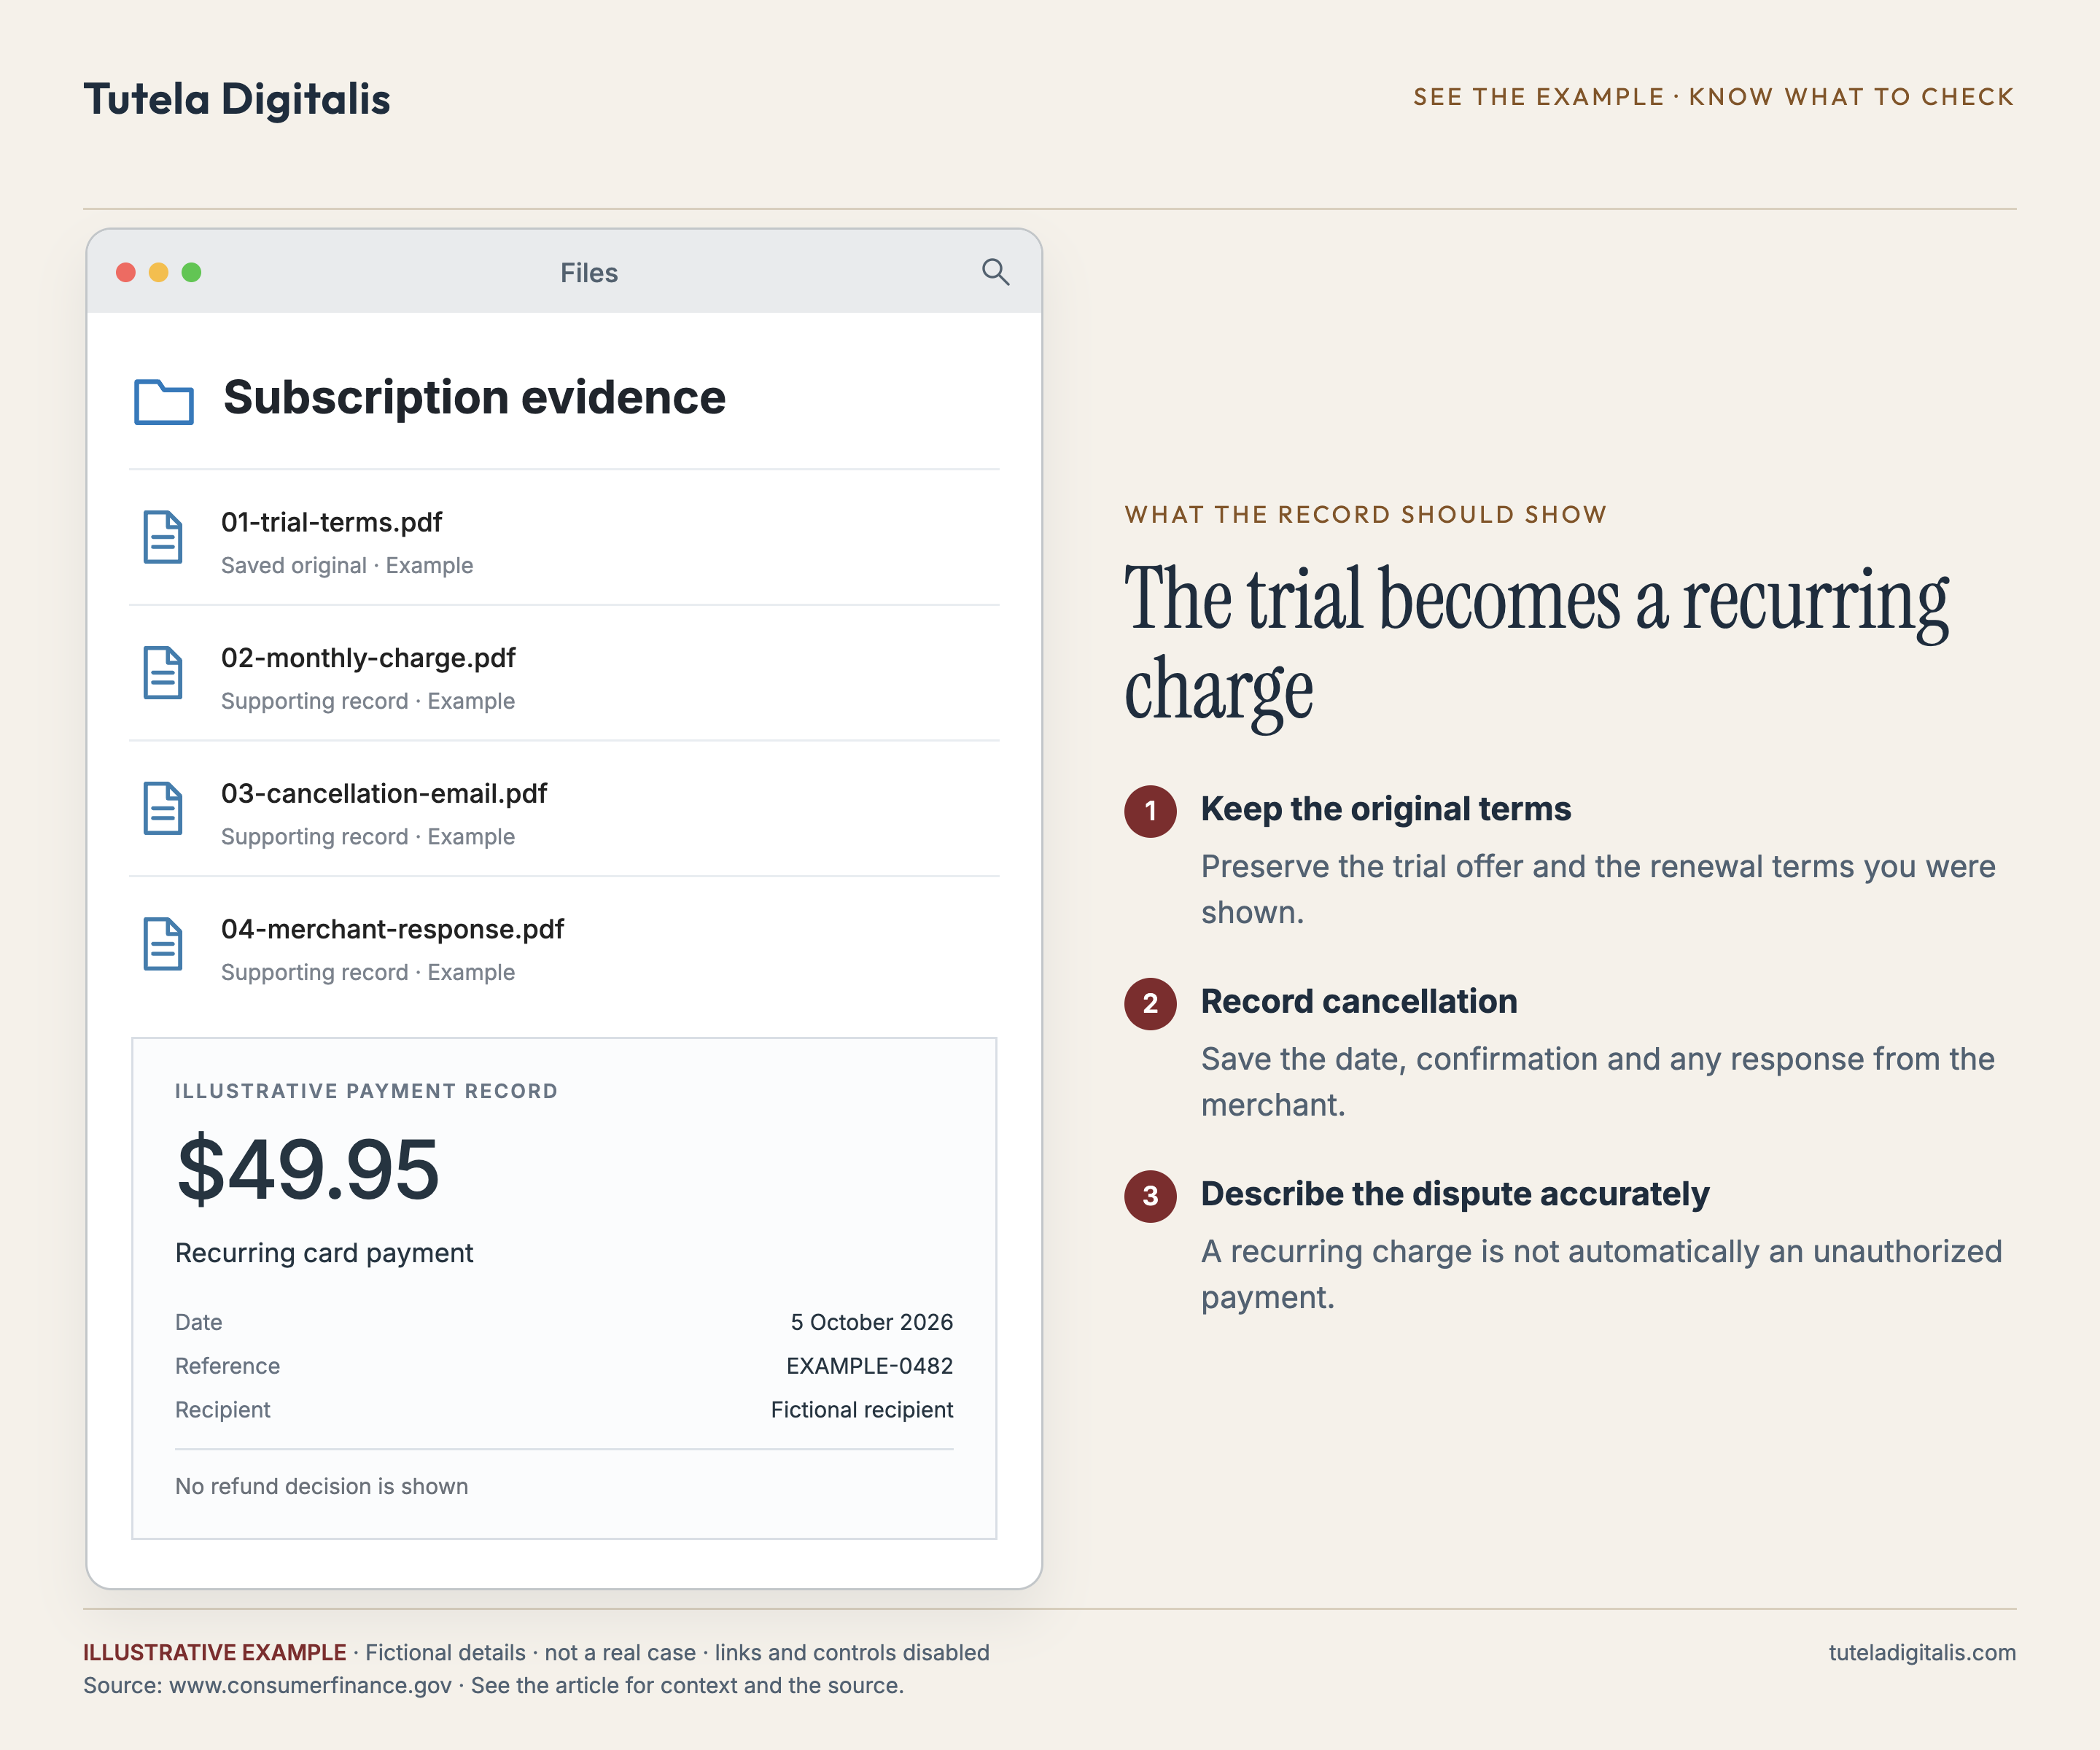
The trial becomes a recurring charge. Illustrative statement and cancellation record with fictional merchant names, amounts and dates. This is not a bank interface. View the source. Open full-size image.Illustration added 6 October 2026.Read the image explanation
Keep the original terms. Preserve the trial offer and the renewal terms you were shown.
Record cancellation. Save the date, confirmation and any response from the merchant.
Describe the dispute accurately. A recurring charge is not automatically an unauthorized payment.
“When customers try to cancel, Uber makes it extremely difficult. Users can be forced to navigate as many as 23 screens and take as many as 32 actions to cancel.”
Federal Trade Commission, announcing its action against Uber over Uber One billing and cancellation (April 2025). These are the FTC’s allegations.
For a long time, the rule on free trials was simple: read the terms, set a calendar reminder, cancel before the trial ends. If you got billed, that was on you for not being careful enough.
That framing was always a little unfair, and in 2026 it is genuinely dangerous. The modern subscription trap is not a careless slip-up by a company that hopes you forget. It can be a polished, tested machine whose entire job is to make signing up frictionless and cancelling painful. If you have ever found yourself paying for something you barely remember subscribing to, and could not work out how to make it stop, skip to “If you are already trapped in one.” You were not careless. You were targeted by design.
Why this works so well
Three forces collided to make the subscription trap so common, and understanding them takes the shame off you entirely:
—Everything became a subscription. Software, streaming, news, fitness apps, AI tools, even kitchen appliances. The recurring-charge model is now the default for most digital products, so a small monthly line on your statement raises no alarms; it just looks normal.
—Dark patterns went professional. Pre-checked boxes, fine print in greyed-out 9-point type, 'subscribe' buttons three times the size of 'no thanks,' and cancellation flows that loop you through retention offers, surveys, and 'are you sure?' modals. These are deliberate design choices, tested for the conversion rate they squeeze out of confused users.
—The federal rule that would have made it simpler was struck down. The FTC's expanded Negative Option Rule, better known as 'Click to Cancel', would have required cancellation to be at least as easy as sign-up. The Eighth Circuit Court of Appeals vacated it in July 2025 on procedural grounds, shortly before it was due to take effect, and the FTC opened a new rulemaking inquiry in March 2026. The simple, universal 'as easy as sign-up' rule most people think they have does not exist. Older protections, including ROSCA, did not disappear.
The money tells the story. In 2025 Amazon agreed to a $2.5 billion settlement with the FTC, which had alleged that it enrolled tens of millions of customers in Prime without their knowledge or consent and made cancellation difficult: $1.5 billion for refunds and a $1 billion civil penalty. Amazon began sending automatic refunds to eligible customers in November 2025 and had paid more than $845 million by September 2026. In April 2025 the FTC also took action against Uber over Uber One billing and cancellation. This is not a fringe annoyance.
How a subscription trap actually works
It is the same machine across almost every variant: streaming, AI tools, dating sites, supplements, software, weight-loss apps. The five-step structure usually runs like this:
1The hook. A free trial, a $0.99 'shipping only' offer, a 50%-off-your-first-month banner, or a pre-checked add-on at checkout. The headline price is what your brain registers and remembers. It is rarely the price you will actually pay.
2The buried disclosure. Somewhere on the sign-up page (typically below the fold, in small grey text, or hidden behind a 'see details' link) sits the part that says: after your trial, you will be charged $X.XX per month, billed automatically, recurring until you cancel. By design, you are not reading this. The page is designed so you do not.
3The conversion to paid. The trial ends. The first real charge hits. It is often timed for 7 or 14 days after sign-up, when you have already moved on mentally and the email confirming the charge looks like a routine receipt. Often there is no email at all.
4The 'just small enough' bill. The monthly charge is calibrated. $9.99, $14.99, $19.99: large enough to make real money over a year, small enough that most people scrolling their statement read past it. Some companies bill weekly precisely so each charge looks tiny, even though the annual cost dwarfs a normal subscription.
5The cancellation labyrinth. When you finally try to cancel, the path is deliberately painful. Hidden in a sub-menu. Behind a 'pause' button you can mistake for cancel. Through a retention offer, a survey, a phone-call-only step, an 'are you sure?' modal, and sometimes a wait period before the cancellation 'processes.' The friction is the point.
The single rule that exposes every variant: cancelling should never be harder than signing up. If signing up took two clicks and cancelling takes a phone call, three menus, and a retention pitch, that asymmetry is the fingerprint of a trap, regardless of how slick the brand looks. The vacated “Click to Cancel” rule was built around exactly this principle. The principle is still right; you just have to enforce it yourself now.
From the field. The Uber One case the FTC brought in April 2025 is a near-perfect specimen of what regulators allege a modern subscription trap looks like. The FTC alleged Uber promised users they would save $25 a month with Uber One, without accounting for the up-to-$9.99 monthly subscription cost in those “savings,” and that some free-trial users were charged before the trial ended. Cancellation, the FTC said, could require users to navigate as many as 23 screens and take as many as 32 actions. Those are allegations, not findings. But read them as a design document: every screen and every extra click is a decision someone made.
The six formats you will run into most
The packaging changes, the dark patterns do not. These are the variants worth knowing by name:
—The free trial that converts silently. Streaming services, AI tools, weight-loss apps, dating sites. You enter a card 'just for verification.' Two weeks later, the recurring bill starts, often without a reminder email before it does.
—The pre-checked add-on at checkout. You buy a product. On the order page, a box is already ticked enrolling you in 'premium support,' a 'wellness club,' or product insurance, billed monthly. You miss it, click 'buy,' and the recurring charge starts that day.
—The $0.99 shipping-only offer. A celebrity-endorsed skin cream or supplement charges you $0.99 for shipping. Fourteen days later, $89.99 lands for the 'full product', and a new bottle arrives every month.
—The weekly-billing app. Less common subscription rhythm: instead of $14.99/month, the app bills $4.99/week. The smaller line on your statement evades attention, while the annual cost is actually higher than a normal monthly subscription.
—The 'pause to save' loop. You go to cancel. The flow offers you a free month or a 50% discount to stay. You accept once, relieved. Six months later you are still paying, and now the cancel button is back behind the same maze.
—The auto-renewing annual subscription. Bills you once a year, so each charge is large but only annoys you once. The renewal email lands in spam or 30 days before the charge, by which time you have forgotten. Dating sites and some news sites are notorious for this.
How to spot a subscription trap before you sign up
Most of these can be caught at the door if you know what to look for. Run any “free” or trial offer through this list:
—A card is required for a 'free' offer. If something is genuinely free, a credit card is rarely necessary. The card is there because the next step is a charge. Treat 'card required for free trial' as a strong signal you are about to be auto-enrolled.
—The recurring price is missing, vague, or hidden. Search the sign-up page for the monthly or weekly amount. If it is in grey 9-point text, behind a 'see details' link, or only appears in the terms-of-service PDF, that is deliberate.
—The 'no thanks' button is hard to find. Pre-checked subscribe boxes, a giant green 'YES' button next to a tiny grey 'skip,' or an upsell page that does not have a visible decline option. These are textbook dark patterns.
—There is no clear cancellation path. Before you sign up, search the site for the cancellation page. If you cannot find one in two clicks, or it requires a phone call, assume cancellation will be a fight.
—The brand or 'celebrity endorser' is suspicious. Free-trial supplement and skincare scams routinely use fake or stolen photos of celebrities to push the offer. A reverse image search and a quick check of the celebrity's verified social accounts usually exposes them.
—The reviews mention billing surprises. Search '[product name] + billing' or '[product name] + cancel' on Reddit, Trustpilot, and the BBB. If half the reviews are people who could not cancel, you have your answer.
The one habit that blunts most of them
Use a virtual or single-use card number from your bank or a service like Privacy.com for any free trial, with a low spend limit, and still cancel before the trial ends. A charge that cannot land is a useful backstop. It is not a cancellation: deleting a virtual card does not end the underlying agreement, and a valid contractual amount may still be owed, so keep the cancellation confirmation too.
If you are already trapped in one
First, no judgment: these things are engineered to slip past careful people. Now move quickly and in this order:
1Try the company's own cancellation flow first. Even when it is painful, a clean cancellation through the company stops new charges fastest and gives you a confirmation and an effective date, which become evidence if you have to escalate. If the button fails or support refuses, record those attempts.
2Email their support directly. Send a written request to cancel and demand written confirmation. Cite your country's consumer-protection law if you know it (FTC for the US, the Consumer Rights Act for the UK, ACL for Australia). The paper trail matters.
3Dispute the incorrect charges with your bank or card issuer. Call the number on the back of your card and describe accurately what happened: you never agreed to recurring billing, you cancelled on a given date, or you were charged more than agreed. An unwanted renewal is not automatically an unauthorized charge. For a US credit-card billing error, the CFPB says to send written notice within 60 days after the charge appeared on your statement. For automatic payments from a bank account, the CFPB describes revoking authorization with the company and telling the bank; some banks might also recommend a stop payment order, so follow your bank’s process and keep a record of the dates.
4Ask the issuer to stop the recurring payment, and do not rely on replacing the card. Card updater services, such as Visa Account Updater, can pass replacement card details to participating merchants so recurring payments continue. Ask specifically about the merchant's recurring-payment authority and any block. In the UK, the FCA says you can ask your card issuer to stop a recurring card payment without contacting the business first, if you tell it by the end of the business day before the payment is due.
5Document the cancellation maze. Screenshot every screen, every retention offer, every dead-end you hit. If you have to escalate to the FTC, your bank, or a class-action firm, those screenshots are the evidence that you did not freely consent.
6Report it. In the US, the FTC at reportfraud.ftc.gov and your state attorney general (state automatic-renewal laws can give you extra rights). In the UK, Report Fraud. In Australia, Scamwatch. Reporting feeds the cases the regulators eventually build, and is separate from your dispute deadline: do not wait for one before starting the other.
Never pay anyone who contacts you offering to “cancel” or “refund” a subscription for an upfront fee. Scam victims of subscription traps are now actively targeted by fake recovery services that promise to make the charges stop or recover what you lost, for a payment. This is a second scam hunting victims of the first. Your bank, the FTC, and reputable consumer-protection bodies will never charge you to dispute a recurring charge, and the FTC notes that eligible Amazon Prime refunds are sent automatically, with no claim needed. Read more about that pattern in our recovery scams piece.
Where this fits in the bigger picture
The subscription trap is not really new. It is the “negative option” (a sale where silence equals consent) given a digital coat of paint and an industrial-design budget. The same design instincts shape the fake stores and dark-pattern checkouts we cover in the shopping guide; the same recovery-scam playbook from our recovery-scams piece shows up the moment victims start asking online how to get their money back. Until a “Click to Cancel” rule (or something like it) returns, your best protections are a documented cancellation, your card issuer’s dispute and recurring-payment processes, a virtual card number as a backstop for anything labelled “free,” and a healthy suspicion of any sign-up flow that asks for a card before it asks for your interest.
Stay sharp, read the small print no matter how small it gets, and hold onto the rule no dark pattern can engineer around: cancelling should never be harder than signing up.
Caught in a subscription you cannot cancel? Let’s untangle it together.
Describe the company, the charge, and what you have tried. A real person reviews every case and replies within 24 to 48 hours. Free, confidential, no pressure.
A subscription trap is any deal, usually a 'free trial' or a tiny $0.99 or $1 offer, that quietly enrolls you in an ongoing monthly charge once the trial ends, with the recurring price buried, the cancellation process deliberately painful, and the bill set 'just small enough' that most people don't notice it for months. It is not always technically illegal. That is the point: it works because it stays just inside the law while exploiting how human attention actually works.
Is it really a scam if I technically agreed to the terms?
It can still be unlawful. For online negative-option offers covered by ROSCA, the FTC explains that businesses must clearly disclose the material terms, get your express informed consent, and give you a simple way to stop recurring charges. If the recurring charge was hidden in greyed-out small print, the 'no thanks' option was harder to find than 'subscribe', or the cancellation flow was far longer than the sign-up flow, that is a dark pattern: a design choice meant to mislead. The FTC sued Amazon over Prime enrollment and cancellation practices, and Amazon agreed to a $2.5 billion settlement in 2025.
How do I cancel a subscription that won't let me cancel?
Try the company's site first, then escalate fast. (1) Email their support asking to cancel and asking for written confirmation and the effective date; keep the email as a paper trail. (2) Ask your bank or card issuer how to stop future recurring payments to that merchant, and dispute specific incorrect charges, describing accurately what happened (never agreed, cancelled before renewal, wrong amount). An unwanted renewal is not automatically an unauthorized charge. (3) Do not rely on replacing the card: card updater services can pass your new card details to participating merchants. (4) If they keep billing after you cancelled, report it to the FTC at reportfraud.ftc.gov. State automatic-renewal laws can give you extra rights.
Can I get my money back for a subscription I forgot about?
Sometimes, and 2025 set a major precedent. After the FTC sued Amazon over Prime enrollment and cancellation, Amazon agreed to a $2.5 billion settlement, including $1.5 billion for refunds, and began sending automatic payments to eligible customers in November 2025; the FTC says eligible customers do not need to file a claim. For your own case, contact the merchant and your card issuer, describe accurately why the charges are wrong ('no clear consent' or 'unable to cancel'), and provide screenshots of the terms and the cancellation maze. For a US credit-card billing error, the CFPB says to send written notice within 60 days after the charge appeared on your statement. Card-network dispute windows vary, so ask. Older charges are harder to recover. Move fast.
What happened to the FTC's 'Click to Cancel' rule?
The 2024 rule is gone, for now. The FTC's expanded Negative Option Rule, widely called 'Click to Cancel,' would have required that cancelling a subscription be at least as easy as signing up. Shortly before it was due to take effect, the Eighth Circuit Court of Appeals vacated it in July 2025 on procedural grounds. The FTC opened a new rulemaking inquiry in March 2026, which is not itself a replacement final rule. But you are not unprotected: ROSCA still requires clear disclosure, express informed consent and a simple way to stop recurring charges for covered online offers, and other federal and state laws still apply.
Can my bank stop a recurring card payment in the UK?
Yes. FCA guidance says you can ask the card issuer to stop a recurring card payment without first contacting the business; tell it by the end of the business day before the payment is due. That stops the payment authority, not any underlying amount you legitimately owe under a contract.
Sources & further reading
Every figure in this piece is drawn from these authorities, rechecked 16 October 2026. Click any of them to verify.