MARKETPLACE SCAMS · ANATOMY OF A CONUpdated 7 October 20269 min readBy Peter
Fake payment screenshot: check the transaction before you release the item.
If you've ever sold something online, you know the moment: a keen buyer, a quick "I just sent it ✅", a screenshot of the payment — and a polite push to ship today. It feels rude to doubt them. That feeling is the whole scam. Here is exactly what that exchange looks like, and the checks to make before goods or money leave your hands.
Verify
Open your own account
Pause
Check before shipping
Keep
Save the original messages
Ask
Use official provider support
The short answer
A fake payment screenshot is a claim a buyer controls, not proof that you were paid. Open your own bank or payment app and check the transaction independently. Do not ship because of a screenshot, send a separate “overpayment” refund, or pay for a supposed Zelle upgrade. Genuine payments can be pending, and an available balance does not guarantee that a payment cannot be reversed.
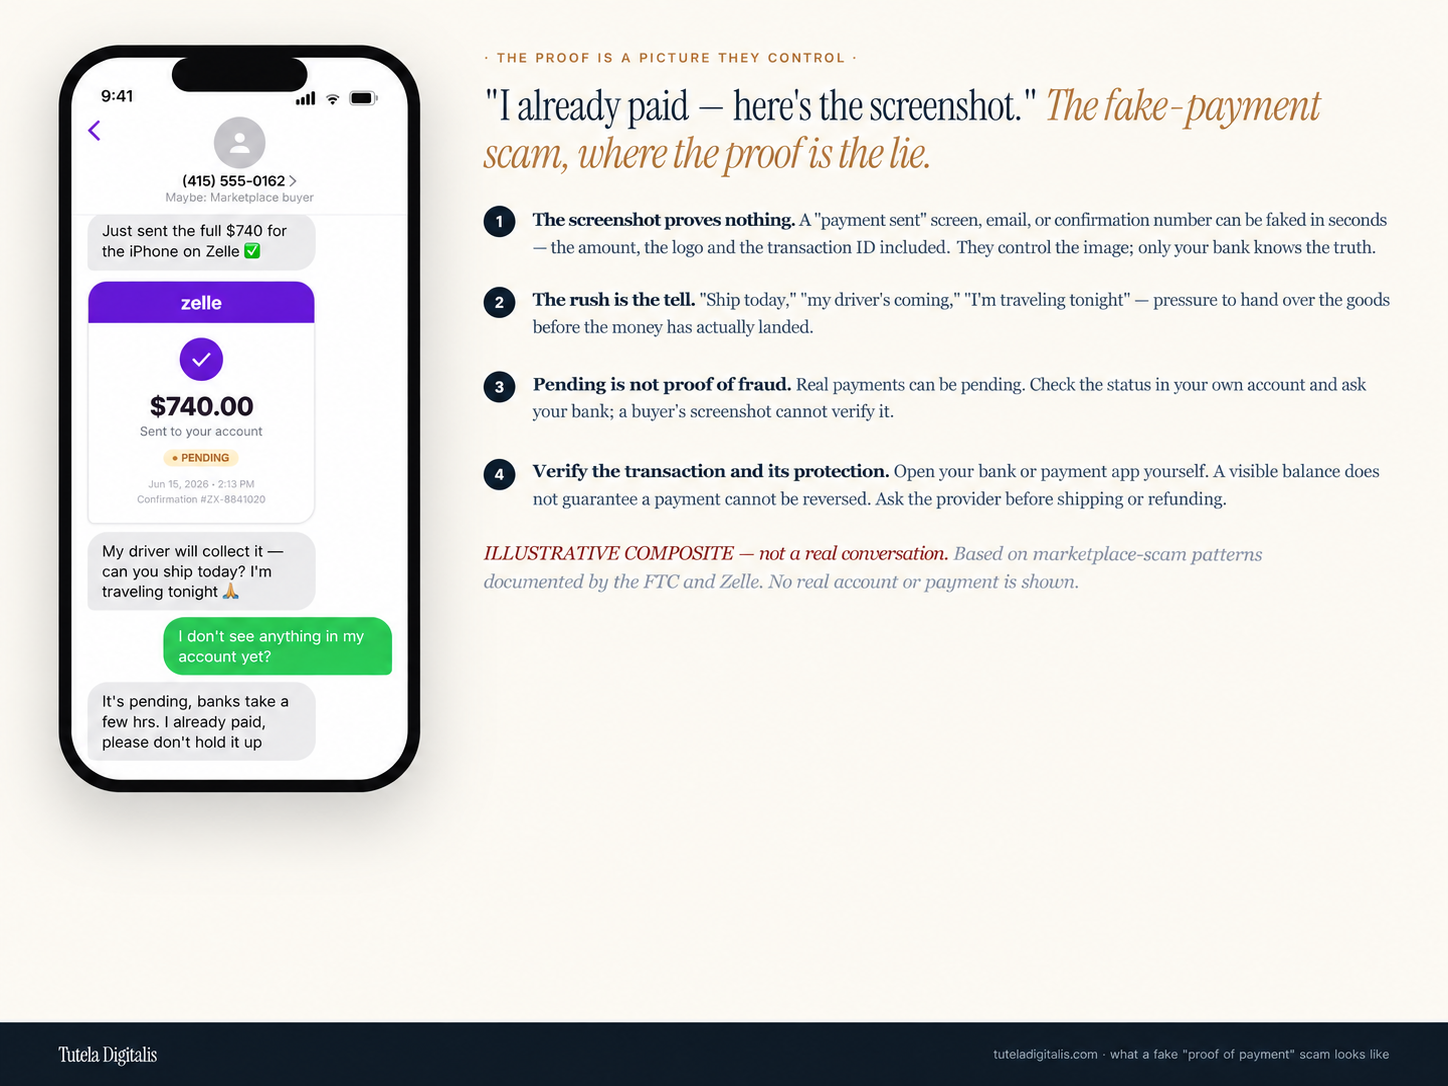
If you, or someone you know, is selling something online right now, look at the picture below before the next "I already paid" message arrives. The scam doesn't rely on a clever fake — it relies on the small social discomfort of asking a friendly stranger to wait while you check. Recognizing that pressure can make it easier to pause the sale.
Illustrative composite of marketplace-scam patterns documented by the FTC and Zelle, not a real conversation or transaction. Pending can be a genuine status; the pressure to act on someone else’s screenshot is the warning.
Most scam advice is written for buyers — how not to get cheated when you pay. This one runs the other way. According to the US Federal Trade Commission, people selling online are routinely targeted with fake payment notices, fake check overpayments, and bogus "verification" tricks, all built to make a seller part with goods or money before a real payment exists. The con works because the seller is the one being reassured: the buyer is eager, the "proof" looks right, and questioning it feels paranoid.
Check the payment, then check the protection. Your own account is the place to verify a transaction. Its presence does not, by itself, mean a payment is final or that a sale is covered. Ask the provider about anything unclear before releasing the item or returning money.
How to spot it: the tells
The fake-payment scam comes in a few flavours, but the fingerprints are consistent:
—The proof is an image they sent you. A screenshot, a forwarded 'receipt', a confirmation number — anything except money you can see in your own account. They control the proof; you control your bank.
—A push to ship before you've checked. 'Can you send it today?', 'my driver is on the way', 'I'm traveling tonight' — urgency designed to move the goods before the payment is verified.
—The 'it's pending' excuse. When you say the money isn't there, you're told it's 'processing' or 'pending for a few hours.' Real transfers can be pending. The warning is pressure to proceed before independent verification, not the status word alone.
—An overpayment and a refund request. The buyer 'accidentally' pays too much and asks you to send the difference back — you refund real money against a payment that was never real.
—A demand to pay to get paid. 'Your account must be upgraded to business to receive this' — you're told to send money to 'release' the payment. Zelle specifically warns there is no paid upgrade to release a payment.
Anatomy of the exchange, decoded beat by beat
The fake-payment scam is a short, social sequence, each step leaning on politeness and momentum. Naming the move at each stage helps you pause, verify the transaction and check the provider’s protection before acting.
1The eager buyer and the instant 'proof'
“Just sent the full $740 for the iPhone on Zelle ✅” — followed by a screenshot of a payment confirmation.
The lever — Social proof + the authority of an official-looking image. A confident claim plus a screenshot that mimics a real app feels like settled fact. The image carries borrowed authority — logo, amount, a confirmation number — and most people read it as a receipt rather than as a picture a stranger made. The eagerness flatters: a fast, full-price buyer is exactly who you hoped for.
The counter — An image is a claim you need to verify. Open your own account independently and check with the provider; a convincing picture cannot establish payment or seller protection.
2The rush to ship
“My driver will collect it — can you ship today? I'm traveling tonight 🙏”
The lever — Manufactured urgency + politeness pressure. A deadline you didn't set — a courier already coming, a trip tonight — pushes you to act before you pause to verify. It also weaponises courtesy: making an eager, apologetic buyer wait feels rude, and that small social friction is exactly what the scam needs you to avoid.
The counter — Pause the sale until you can verify it through your provider. A buyer’s timetable is not a payment-verification method.
3The 'it's pending' stall
“It's pending, banks take a few hrs. I already paid — please don't hold it up.”
The lever — Plausible delay + reframing your caution as the problem. When you notice the money isn't there, 'pending' supplies a reasonable-sounding reason to proceed anyway — and quietly flips the script so that your sensible caution becomes you 'holding things up.' It buys the scammer the only thing they need: the window between your trust and your verification.
The counter — Pending can be genuine. Check the transaction yourself and ask the bank if needed; a stranger’s screenshot cannot establish whether you should ship.
4The twist: overpayment, or 'upgrade to receive'
“Oops, I sent $1,200 by mistake — can you send the $460 back?” or “Your account needs a business upgrade to release the funds — send $200 and I'll refund it.”
The lever — Reciprocity + paying to get paid. Both twists turn the scam profitable in cash, not just goods. The overpayment exploits fairness — they 'overpaid', so refunding 'their' money feels only right. The 'upgrade' exploits hope — a held payment you can free by sending a little first. The separate payment you send can become a second loss. The claimed original payment may be fabricated or may later be reversed.
The counter — Do not send a separate refund or pay for a supposed Zelle upgrade. Ask the provider to investigate the original transaction and handle any legitimate return.
Then comes the second loss — or the second scam. A payment that "arrives" can still be clawed back later if it was funded by a stolen account or a bad check, leaving you minus the item and the money. And people who lose money this way are often contacted again by a fake "recovery" service promising to get it back for a fee — itself a recovery scam. Verify advisers independently; do not trust an unsolicited promise or send account access.
Can a genuine payment show as pending?
Yes. Zelle explains that pending can mean the recipient has not enrolled the relevant phone number or email. Ask your bank about a payment you cannot verify; do not treat either a “pending” label or an attractive screenshot as a verdict.
Does money showing in my account mean it is safe to refund?
No. The FTC’s fake-check guidance explains that banks make funds available before discovering some checks are fraudulent. A later reversal can leave you responsible for money you sent elsewhere. Ask the provider to handle an unexpected payment; do not create a second transfer to a buyer’s chosen account.
Seller protection also has conditions. PayPal’s US policy, for example, identifies eligibility in Transaction Details and requires evidence and other conditions. It does not cover every sale or dispute. Read the policy for your country and payment type before relying on it.
What to do before shipping, and after a loss
1Verify the transaction independently. Open your own bank or payment app. Check the transaction and ask official support about anything missing, pending or unexpected. Do not sign in through a buyer’s receipt link.
2Pause before releasing the item. Compare the transaction with the sale and check the provider’s seller-protection conditions. A driver arriving or a buyer traveling does not change those checks.
3Do not make a separate refund or upgrade payment. Ask the provider to investigate an unexpected payment and handle any legitimate return. Do not send money to a buyer’s nominated account.
4Contact the courier and provider after a loss. Ask the courier whether delivery can be stopped and report any money you sent to your bank or payment provider. Keep the original listing, conversation, receipts and tracking record. A stop or refund is not guaranteed.
5Report the account and scam. Report the account to the marketplace and the scam to the relevant official reporting service. Do not engage unsolicited recovery offers.
From the field. The fake-payment scam barely qualifies as a hack — it's a manners exploit. There's no malware and no clever forgery you're meant to fall for; there's an eager buyer, an official-looking picture, and the quiet social cost of asking them to wait. Careful, honest people get caught precisely because they're honest: they extend the trust they'd want extended to them. You don't beat this by becoming suspicious of everyone. You beat it with one boring habit that owes the buyer nothing — a buyer’s confidence is not payment evidence. Check the transaction with the provider and understand the protection before the item moves.
A buyer sent "proof" and you're not sure? Send it to us first.
Describe the messages and listing without sharing passwords, security codes or full account details. A free case review can help organize the warning signs. Your bank or payment provider must verify the payment.
A buyer sends an image or receipt claiming to prove a payment, then pressures a seller to release an item or return money. The image can be fabricated. Check the transaction through your own bank or payment service, opened independently. A screenshot is evidence of what the buyer claimed; it is not confirmation that you were paid.
How can I tell if a payment screenshot is fake?
You cannot reliably authenticate a payment by examining the picture. Even a convincing transaction ID or logo can be copied. Check the payment in your own account and ask the provider about anything unclear. Do not use a phone number, login link or support contact supplied by the buyer.
Can a genuine Zelle payment be pending?
Yes. Zelle says a payment can be pending when the recipient has not enrolled the relevant email address or mobile number. Pending is not proof of fraud, but a screenshot of that status is not permission to ship. Check through your bank; do not follow a buyer's instructions to release the payment.
What is the Zelle business account upgrade scam?
A fake message says you must send money to upgrade your account before a payment can arrive. Zelle warns that there are no such account upgrades. Do not send the buyer money or call a support number in the message. Open your own banking app or contact your bank independently.
Should I return a buyer's accidental overpayment?
Do not send a separate payment to the buyer or to another account they nominate. Contact your bank or payment provider through its official channel and ask it to investigate and handle any legitimate return. A deposit showing in your balance can still prove invalid, particularly with a fake check.
I already shipped the item or sent money. What should I do?
Contact the courier to ask whether delivery can be stopped, and report the payment to your bank or provider immediately. Preserve the listing, original messages, receipts and tracking record. Report the account to the marketplace. A stop or refund is not guaranteed, and an unsolicited recovery offer can cause another loss.
Sources & further reading
Reviewed 7 October 2026. Corrected claims about pending payments, cleared funds and refund safety in the text and illustration. The example is a clearly labelled composite, not a real victim’s exchange.